Scooter and Moped Finance in the UK — A Complete 2026 Guide
💡 Key Takeaway
Need to finance a scooter or moped in the UK? Here's how two-wheeler finance works in 2026 — products, costs, deposit requirements, and what lenders look for.
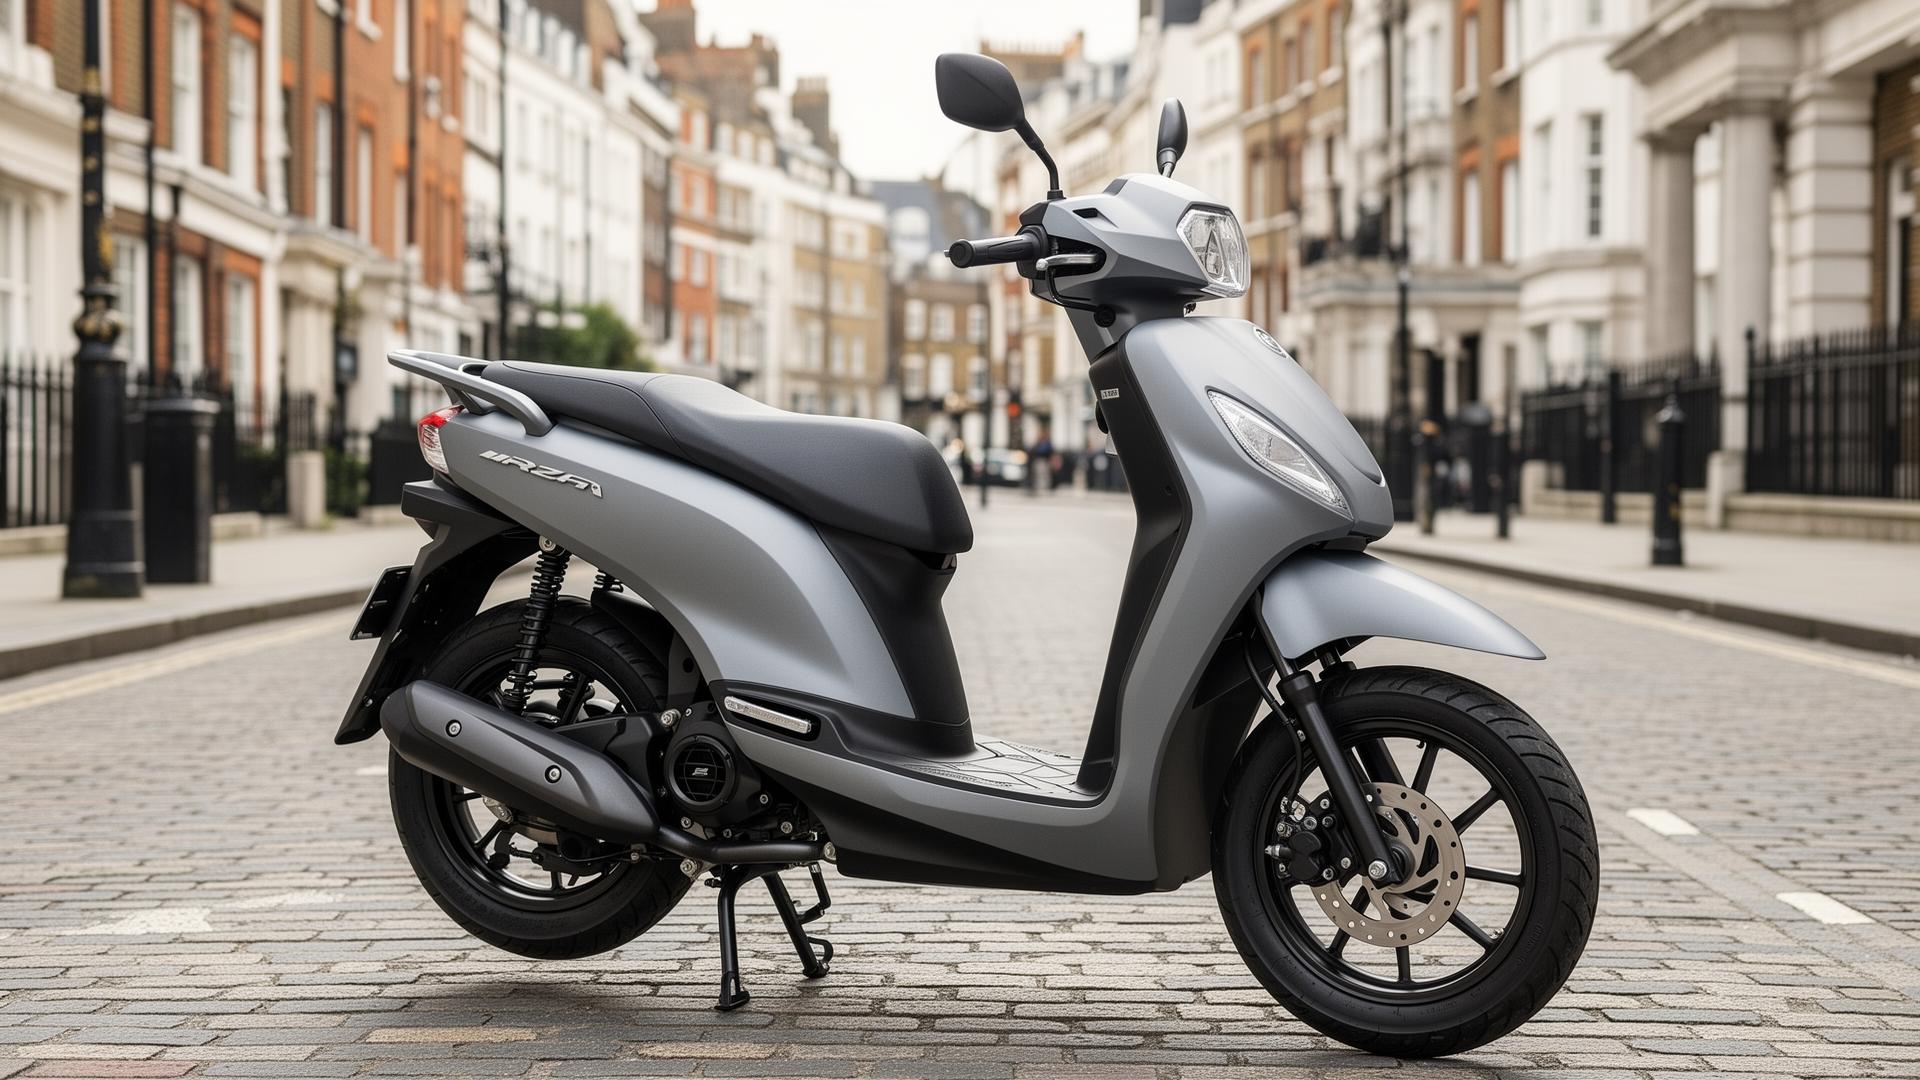
A scooter or moped can be a genuinely practical solution for commuting, city travel, or reducing running costs — and the good news is that financing one in the UK is straightforward in 2026. 🛵
Whether you're looking at a 50cc learner-legal moped or a 125cc commuter scooter, there are several finance routes available. Here's everything you need to know.
Finance Options for Scooters and Mopeds
The main options are:
- Hire Purchase (HP) — fixed monthly payments over 12–36 months, you own the scooter at the end. The most common route for two-wheelers.
- Personal loan — unsecured borrowing from a bank or lender, used to buy the scooter outright. Can offer competitive rates for buyers with good credit.
- PCP (Personal Contract Purchase) — less common on scooters and mopeds due to lower vehicle values, but available on higher-value models.
- Dealer finance — many scooter dealers offer in-house HP arrangements, often via a specialist two-wheeler finance provider.
HP is generally the most accessible and widely offered option for scooters and mopeds from mainstream dealers. 💡
What Values Can Be Financed?
New scooters and mopeds range from around £1,500 for a basic 50cc up to £8,000–£10,000 for a quality 125cc or larger-engined model from brands like Honda, Yamaha, Piaggio, or Vespa.
Most lenders have a minimum loan amount — typically £1,000–£1,500 — which means very low-value machines may not qualify for HP. A personal loan may be more suitable for cheaper models.
Used scooters can also be financed, though lenders will assess age and condition. A used scooter with a full service history and current MOT is straightforward for most specialist lenders. ✅
What Deposit Is Typically Required?
For scooter and moped HP finance, a deposit of 10–20% of the vehicle value is typical. On a £2,500 scooter, that's £250–£500 — very achievable for most buyers.
Some deals are available with no deposit, particularly from dealer partnerships with finance providers, though these will carry higher monthly payments.
What Will Lenders Check?
The same affordability and credit checks apply as for any consumer finance:
- Proof of income — payslips, bank statements, or tax returns if self-employed
- Credit history — missed payments, defaults, or CCJs may limit your options
- Identity and address verification
- Age — most lenders require applicants to be 18 or over
For younger buyers (18–21), a guarantor arrangement may be needed if credit history is limited. 💰
Do You Need Insurance Before Applying?
You'll need fully comprehensive insurance in place before most finance lenders will release funds. Get insurance quotes early — scooter insurance for young or new riders can be higher than expected, and it's worth factoring this into your monthly budget.
CBT (Compulsory Basic Training) is also required before riding a moped or 125cc on the road — if you haven't completed this, factor in the cost and timing before committing to finance.
Electric Scooters — A Growing Option
Electric scooters (L1e/L3e category road-legal models, not stand-up e-scooters which remain illegal on UK roads) are increasingly popular and can be financed on HP in the same way as petrol models. Running costs are lower, and several manufacturers now offer compelling electric options in the 125cc equivalent class.
Talk to WFYA About Two-Wheeler Finance
At We Finance Your Asset, based in Reading, Berkshire, we help buyers across the UK find finance for all types of vehicles — including scooters, mopeds, and motorcycles.
👉 Visit wefinanceyourasset.co.uk to explore your options today.