Hot Hatch Finance — How UK Buyers Can Fund a Performance Hatchback in 2026
💡 Key Takeaway
Hot hatch finance in the UK explained. PCP, HP and lease options for Civic Type R, Golf R, M135 and more. WFYA in Reading covers the UK.
The hot hatch is still the UK's favourite "everyday performance" car. 🚗 Practical enough for the school run, fast enough to put a grin on your face on the way home — and in 2026, the choice has never been better.
From the Honda Civic Type R to the Volkswagen Golf R, BMW M135 and the Cupra Leon, hot hatches sit in a sweet spot: high spec, real-world usable, and well supported by UK finance lenders.
If you're in Reading, Berkshire or anywhere else in the UK and thinking about funding one, here's how the finance options stack up — and how to get the right deal for the right car.
What Counts as a "Hot Hatch" in 2026?
The classic recipe is simple: a small or medium hatchback with a properly tuned engine, sharper suspension, and styling that hints at what's underneath. In 2026, that recipe now stretches across petrol, hybrid and full-electric.
Some of the most popular hot hatches funded by UK buyers right now include:
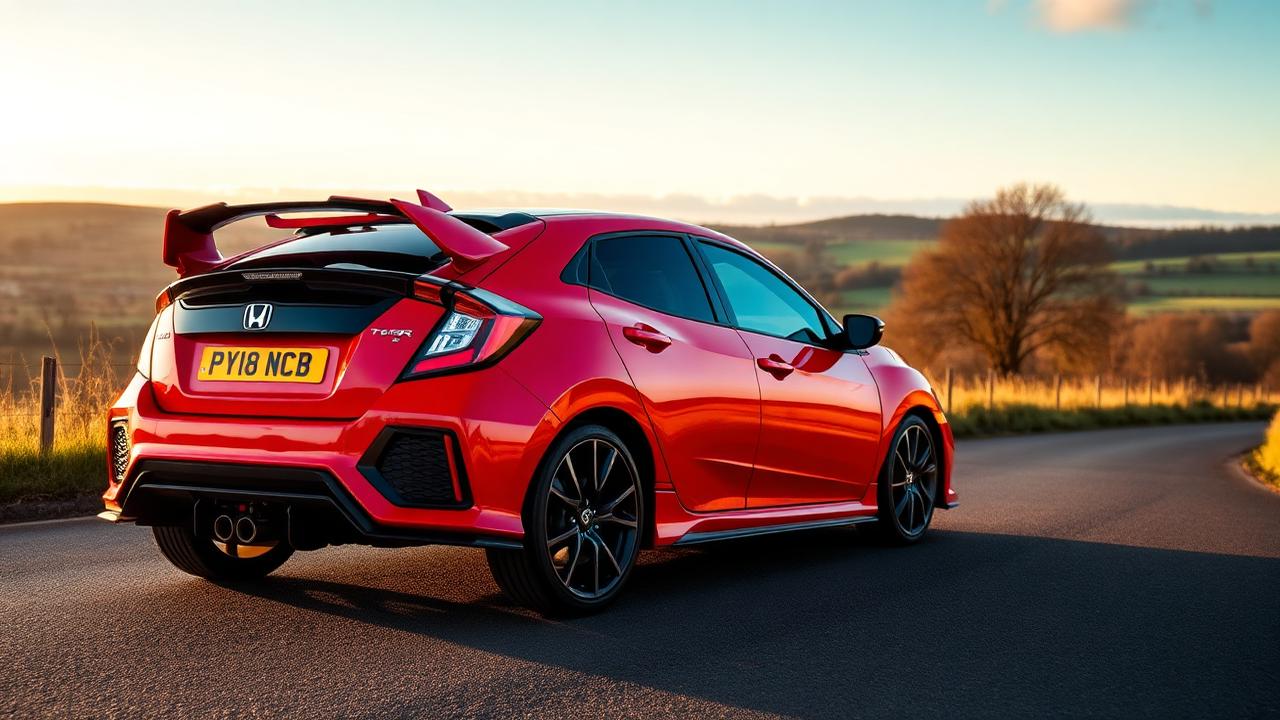
- Honda Civic Type R — still the benchmark front-wheel-drive performance hatch
- VW Golf R / Golf GTI — daily-usable, all-weather grip with the R
- BMW M135 xDrive — premium badge, four-wheel drive, strong residuals
- Audi S3 / RS3 — five-cylinder noise, quattro reassurance
- Cupra Leon — sharply priced and sharply styled
- Hyundai i30 N / Ioniq 5 N — combustion icon plus an electric flagship
- MINI JCW / Cooper Electric — go-kart feel, now in EV form too
Each one has its own typical buyer — and a slightly different finance picture.
Best Finance Options for a Hot Hatch
Most UK buyers choose between three main routes:
- PCP (Personal Contract Purchase) — lower monthly payments, optional balloon at the end, easy to change car
- HP (Hire Purchase) — fixed monthlies, you own the car at the end, no mileage limits
- Personal Contract Hire (PCH) — straight lease, hand the car back at the end of the term
Each has its place. ✅
PCP often wins on flexibility and brochure prices. HP wins for buyers who want to keep the car long-term and avoid mileage worries. PCH suits drivers who like a new car every two to four years and don't want any end-of-term decisions.
PCP for Hot Hatches — What to Watch
PCP works particularly well on hot hatches with strong residual values, like the Civic Type R, Golf R and BMW M135. Lower depreciation means a better balloon and a healthier monthly.
Key things to check:
- Annual mileage limit — UK averages of 8,000–10,000 miles often suit, but check carefully
- End-of-contract damage charges — track use can show up at handback
- Balloon vs market value — if values stay strong, you may have positive equity
- The APR — manufacturer offers can look good but always compare with broker rates
For UK buyers planning the odd track day, this is where PCP can get expensive — HP or PCH may suit better.
HP for Hot Hatches — Why It's Still Popular
For drivers who genuinely want to keep the car, Hire Purchase is often the cleanest deal. You pay a deposit, fixed monthly payments, and at the end the car is yours.
It's a strong choice when:
- You plan to keep the car beyond three or four years
- You expect high mileage and don't want PCP penalties
- You're modifying the car (within reason and within insurance rules)
- You want certainty — no balloon, no surprises at the end
For higher-value hot hatches (RS3, M135, Type R), HP also avoids the awkward question of negative equity later.
Electric Hot Hatches and Finance
The new wave of EV hot hatches — Hyundai Ioniq 5 N, MINI JCW Electric, Alpine A290 — comes with stronger manufacturer subsidies in 2026 but more uncertain residuals.
That makes PCH or short-term PCP attractive: you get to enjoy the latest tech, then hand the car back when better range and battery tech arrive. 💡
For Reading and Berkshire buyers with home charging, an EV hot hatch can be cheap to run on top of a finance deal — especially with smart tariffs.
How to Get the Best Hot Hatch Finance Deal in the UK
A few practical tips that usually save real money:
- Compare broker rates against the dealer's offer — brokers like WFYA work with multiple lenders
- Don't just chase the lowest monthly — check the total amount payable
- Bigger deposits often unlock lower APR tiers
- Match the term to how long you'll really keep the car (typically 3–5 years)
- Ask about gap insurance, especially on higher-spec models
A good broker should explain all of this clearly — without nudging you into the deal that pays them best.
Final Thoughts — The Right Hot Hatch on the Right Finance
The 2026 hot hatch market is genuinely exciting. Combustion legends are still here, EV options are getting properly fast, and there's a finance product to suit just about every UK driver.
If you're in Reading, Berkshire or anywhere else in the UK and ready to fund your next performance hatchback, We Finance Your Asset can help you compare PCP, HP and lease deals across multiple lenders.
👉 Visit wefinanceyourasset.co.uk for tailored hot hatch finance — straightforward, regulated, and built around the car you actually want.