Financing a Cat S or Cat N Car — What UK Buyers Need to Know in 2026
💡 Key Takeaway
Thinking of buying a Cat S or Cat N car on finance in the UK? Most lenders won't touch them — but some will. Here's what buyers need to know in 2026.
Insurance write-off categories can be confusing — and when it comes to finance, they matter a great deal. If you're considering buying a Cat S or Cat N vehicle, understanding how lenders view these cars is essential before you commit. 🚗
The good news: finance on Cat S and Cat N cars is possible. The bad news: your options are narrower than on a clean-title vehicle, and you'll need to know where to look.
What Do Cat S and Cat N Mean?
These are two of the four insurance write-off categories used in the UK:
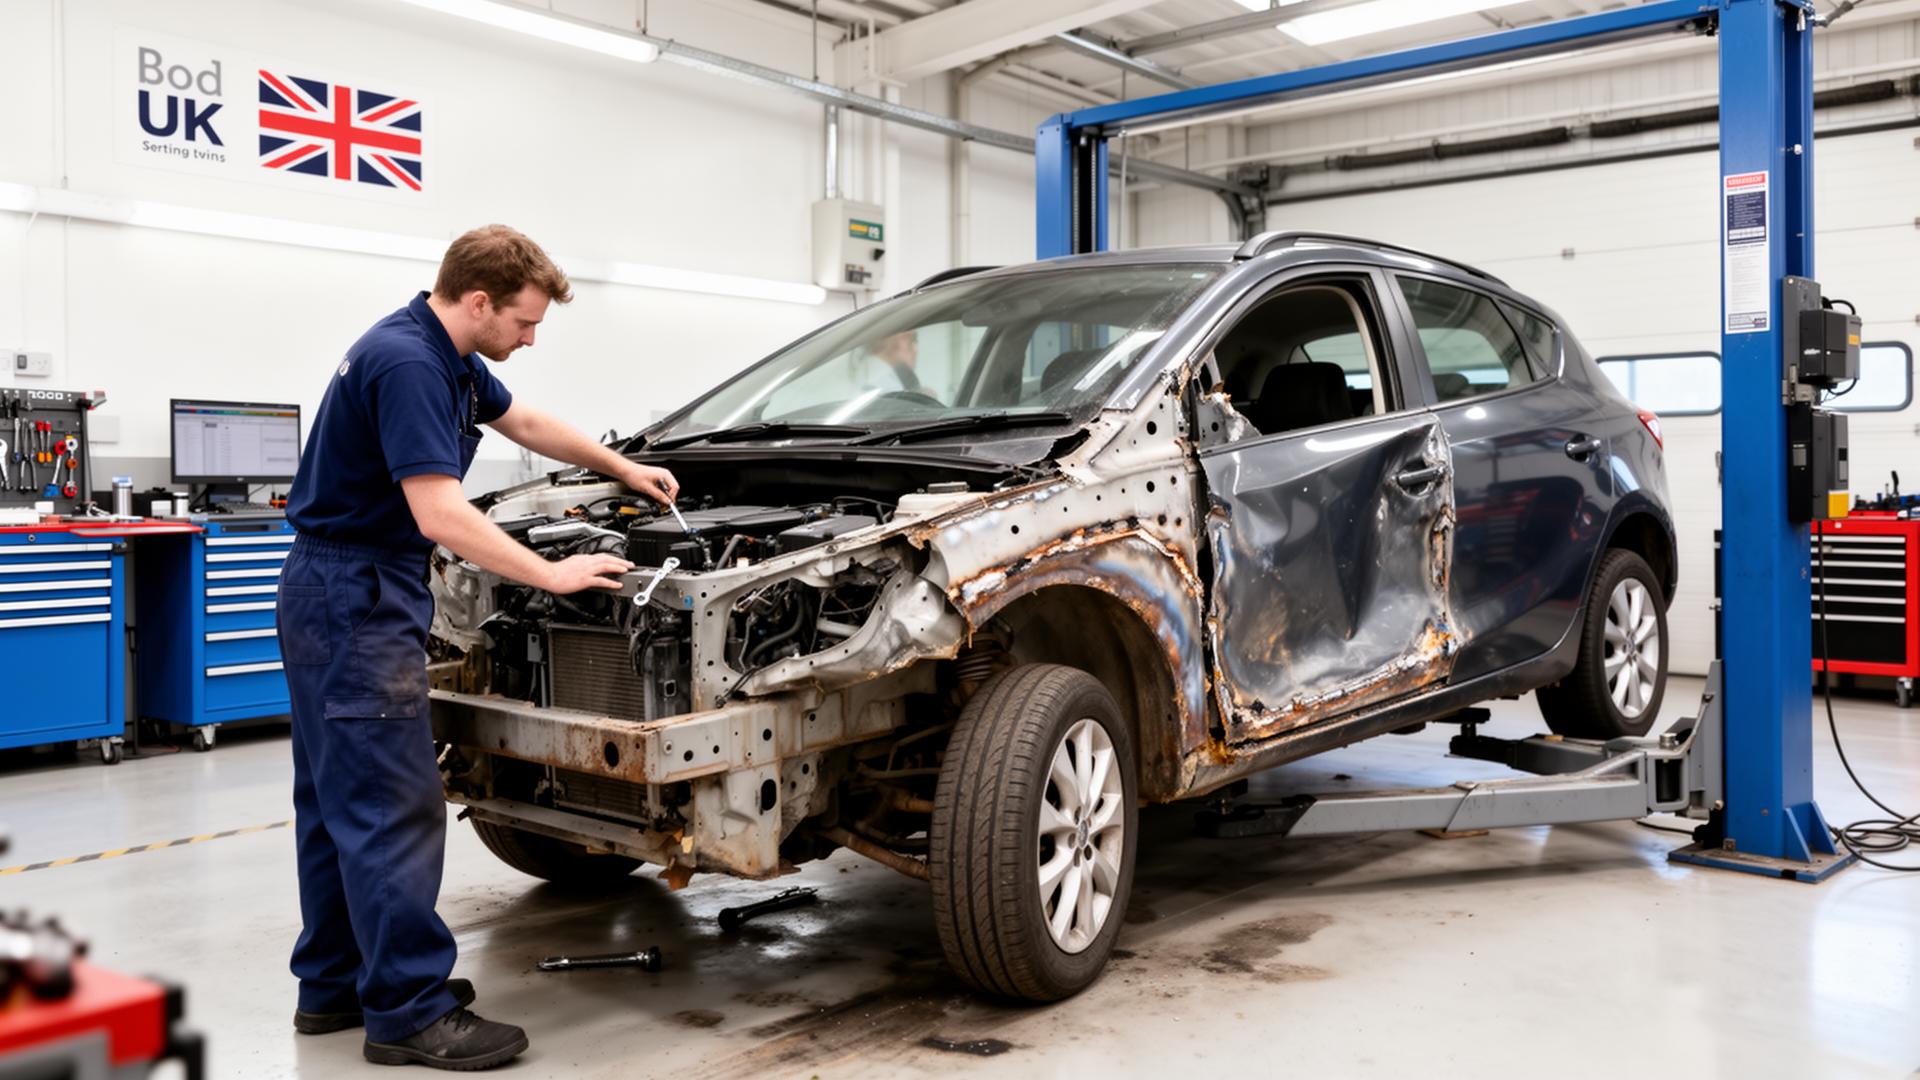
- Cat S (Structural damage) — the vehicle has suffered structural damage (chassis, crumple zones, etc.) but has been repaired to a roadworthy standard. It must be re-registered with the DVLA before it can be sold.
- Cat N (Non-structural damage) — the vehicle was written off due to non-structural damage (electrics, cosmetics, airbags) but again has been repaired. No re-registration is required, but the history is permanently recorded.
Both categories replace the old Cat C and Cat D classifications. The key point: once written off, the marker stays on the vehicle's history permanently — it will show on any HPI or vehicle history check.
Why Do Lenders Care?
Lenders care because their security — the vehicle — has a compromised history. A write-off marker affects:
- Residual value — Cat S and Cat N cars are typically worth 20–40% less than equivalent clean-title vehicles
- Resale risk — if the lender needs to repossess and sell the car, they'll recover less
- Insurability — some insurers load premiums significantly on write-off vehicles, or decline cover altogether
Mainstream lenders — the ones used by most dealerships — will almost always decline applications on Cat S or Cat N vehicles. This isn't necessarily a reflection of your creditworthiness; it's a policy decision about the asset itself. 💡
Which Lenders Will Finance a Cat S or Cat N Car?
Specialist and sub-prime lenders do exist who will consider these vehicles, but it comes with conditions:
- The repair must be professional and verifiable — ideally with documentation
- The vehicle should be structurally sound and have a current MOT
- The loan-to-value ratio will typically be assessed on the write-off value of the vehicle, not the asking price
- You may need a larger deposit to reduce the lender's exposure
Cat N vehicles are generally easier to finance than Cat S, because the damage was non-structural. Cat S cars face more scrutiny due to the nature of the repair involved.
What About Private Purchases?
Buying a Cat S or Cat N car privately — rather than from a dealer — adds another layer of complexity. Lenders are less comfortable with private purchases of write-off vehicles, as there's no dealer accountability and the repair history may be harder to verify.
If you're buying privately, a full independent inspection by a qualified engineer is strongly recommended before you approach any lender. ✅
What Should You Check Before Buying?
Always run a full vehicle history check (HPI, Experian Autocheck, or similar) to confirm the write-off category and see whether repairs have been recorded. Also check:
- Is the repair documented? — receipts, photos, and engineer reports all help
- Has it been MOT'd post-repair? — a current MOT is essential
- What does the V5C show? — Cat S vehicles require DVLA re-registration
- Can you get it insured? — get insurance quotes before committing to purchase
Is It Worth It?
Cat S and Cat N cars can represent genuine value — often priced significantly below market. If the repair is solid, the history is transparent, and you can obtain adequate insurance, the financial case can make sense. 💰
But the narrower finance market, higher deposit requirements, and insurance complications mean it's not the right choice for everyone. A clean-title vehicle financed at a competitive rate often works out more straightforward overall.
Talk to WFYA About Your Options
At We Finance Your Asset, based in Reading, Berkshire, we work with lenders experienced in non-standard vehicle histories. If you've found a Cat S or Cat N car you're interested in, talk to us before you commit.
👉 Visit wefinanceyourasset.co.uk and tell us about the vehicle — we'll let you know what's achievable.