Camper Van Conversion Finance — A 2026 UK Guide
💡 Key Takeaway
How to finance a camper van conversion in the UK in 2026 — funding the van, the build, or both. A practical guide from WFYA in Reading.
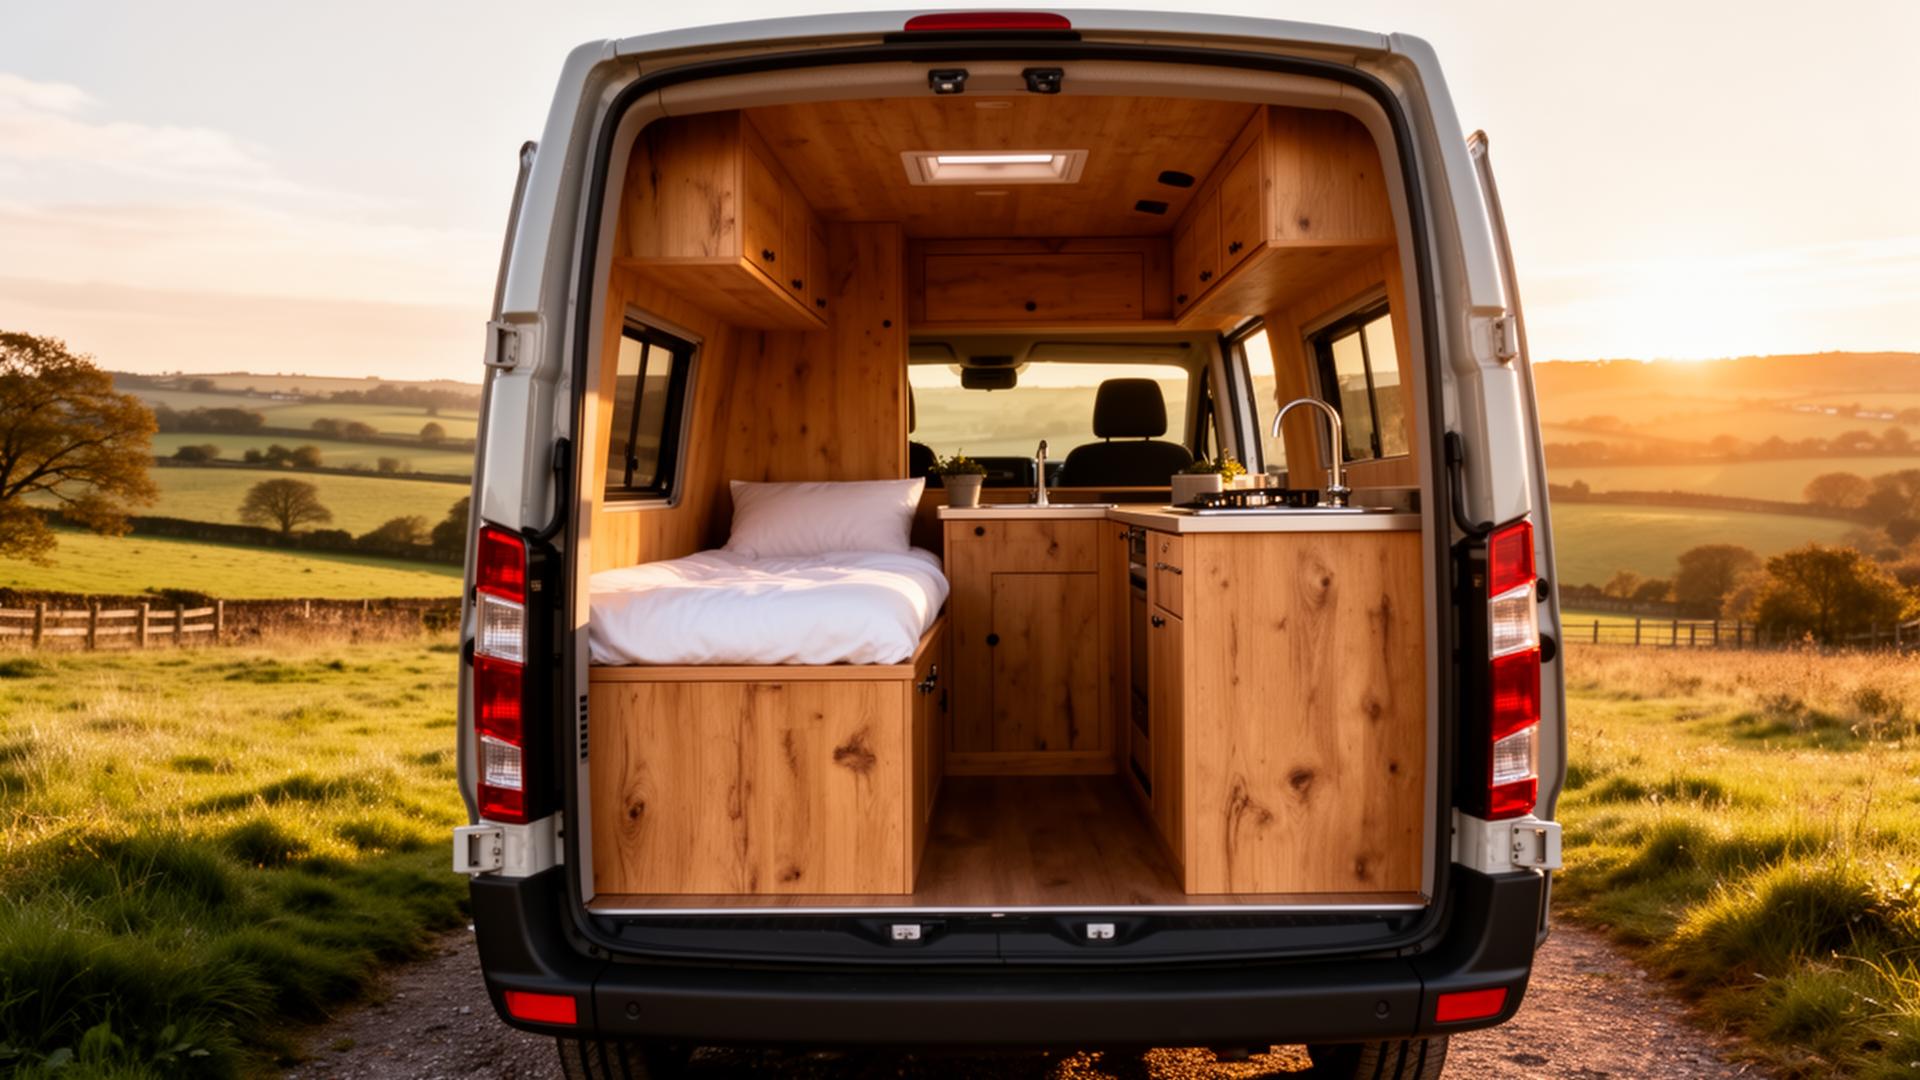
The UK camper van scene is bigger than ever in 2026. From weekend warriors in Berkshire to full-time vanlifers crisscrossing the country, more people are converting vans into homes on wheels — and many need finance to do it. 🚐
But camper van conversion finance is a niche corner of the lending world. Banks don't always understand it, and high street lenders rarely cover the build cost. Here's how it actually works in the UK in 2026.
Why Camper Van Conversion Finance Is Different
A standard camper van loan is straightforward — the van exists, it has a value, the lender has security. A conversion project is messier:
- The base van might be cheap, but worth far less unconverted than after the build
- The conversion adds value, but only once it's complete and DVLA-recognised
- Self-build vans are harder for lenders to assess and insure
That means most buyers need to think about two pots of money: one for the van, one for the conversion. ✅
Option 1: Finance a Pre-Converted Camper
If you're buying a finished, professionally-converted camper van, finance is simple. Specialist camper van finance products treat it like any other leisure vehicle:
- Hire Purchase (HP): spread the cost over 2-7 years, own it at the end
- Lease Purchase: lower monthly payments with a final balloon
- Secured loans: longer terms (up to 10 years) for higher-value vans
Professional conversions from established UK builders typically command higher resale values, which means lenders are comfortable funding them. You'll usually need a 10-20% deposit.
Option 2: Finance the Base Van + Conversion Separately
Going down the self-build route? You'll typically need:
- Finance for the panel van itself — standard vehicle HP or a personal loan
- Funding for the conversion — savings, a personal loan, or a home equity option
Most mainstream car finance lenders won't fund a "build budget" because there's no asset to secure against the work yet. Some specialist asset finance brokers will help structure this — combining vehicle finance with a personal loan top-up.
Option 3: Refinance Once the Conversion Is Done
A common approach in 2026 is to refinance the camper after conversion. Once the build is complete, the van is reclassified by DVLA as a "motor caravan" and revalued — often well above the cost of the base van plus the build.
That equity can be used to:
- Pay off the original van finance
- Reimburse some of the build cost
- Free up cash for further upgrades
This route works best for high-quality conversions with proper documentation — receipts, photos, and ideally a professional habitation check. 💡
What Lenders Look At for Camper Finance
UK lenders considering camper van finance applications will typically check:
- Credit history — clean is best, but specialists can help with adverse credit
- Affordability — your monthly disposable income vs the proposed payment
- Vehicle age and mileage — older vans (10+ years) need specialist lenders
- Conversion quality — for finished campers, who built it and to what standard
Whether you're in Reading, Berkshire, or anywhere across the UK, the right broker can match your project to a lender that actually understands campers.
DVLA Reclassification — Why It Matters for Finance
Once your conversion meets DVLA's standards (fixed bed, cooking facility, water storage, seating, etc.), you can apply to have your V5C reclassified as a motor caravan. This usually:
- Increases the van's resale value
- Can lower insurance costs
- Helps unlock specialist refinance options
It's a small admin job that can have a big finance impact. Worth doing as soon as the build qualifies.
Common Mistakes to Avoid
A few traps we see regularly:
- Underestimating the build cost — it almost always runs over
- Choosing the wrong base van — high-mileage diesels can fail emissions zones
- Skipping insurance checks — specialist camper insurers ask very different questions
Plan finance and the build together, not separately. 🚐💰
Need Camper Van Finance? Talk to WFYA
At We Finance Your Asset, based in Reading, Berkshire, we work with specialist UK lenders who understand camper vans, conversions, and leisure vehicles. Whether it's a finished pro-build or a self-build project, we'll help structure finance that works.
👉 Get in touch today for tailored camper van finance across the UK.